Posts

Too Much of a Good Thing: The Hidden Perils of Capital Hoarding

by That One Consultant You Hired and Then Ignored

If you’re a board member at a credit union, chances are you’ve said it. Maybe in a hushed boardroom voice, maybe with great conviction over lunch, maybe carved into stone tablets. It goes something like this:

“You can never have too much capital.”

Cue the heavenly choir and the flutter of regulatory examiners descending on clouds of GAAP. Capital, after all, is safety. Capital is security. Capital is your warm, fuzzy blanket on a cold night of economic uncertainty.

Except—and please, clutch your pearls tightly here—you can have too much of it. Yes, really. And when you do, it’s not just inefficient. It’s strategically dangerous.

Let’s talk about it, shall we?

Capital: From Safety Net to Strategic Straitjacket

First, let’s get the obvious out of the way. Capital is good. Regulatory capital is essential. You need it. The NCUA says so, and if the NCUA says jump, most credit unions are halfway to orbit before they ask how high.

But capital is a tool, not a trophy. When your capital ratio drifts into the teens— 13%, 14%, 15% and beyond—you’re not just safe. You’re overdressed for the occasion.
Imagine showing up to a beach party in full medieval armor. That’s what it’s like running a 15% capital ratio in today’s credit union market. Impressive? Sure. But also a bit ridiculous, and not particularly helpful when it’s time to swim—or compete, innovate, or grow.

The Law of Diminishing Return on Paranoia

Many boards live by a simple mantra: More capital equals more safety. It’s neat. It’s easy. It’s… mathematically adorable.

But here’s the truth: every extra dollar of capital that sits unleveraged on your balance sheet is a member dollar not working, not producing value, not returning benefit.

Imagine telling your members, “We’ve taken your money, and we’re keeping it locked away in a vault, doing nothing, because someday the sky might fall. And if it doesn’t? Well, at least we felt warm and fuzzy.”

Not exactly the value proposition credit unions are known for.

And if your board’s idea of risk management is “hoard capital like it’s 2008 and Ben Bernanke just texted ‘brace yourself,’” then you’ve essentially traded strategic growth for a very expensive security blanket.

The Catastrophe That Never Quite Arrives

Boards often justify massive capital buffers by invoking a theoretical calamity so devastating it would make Mad Max look like a municipal planning meeting.

“We need to be ready for the worst-case scenario.”

Great. Let’s play that out.

Say a 500-basis-point rate shock, a recession, a regulatory overhaul, and a complete collapse of consumer confidence all hit at once. Terrifying? Yes. But unless your balance sheet is made entirely of subprime balloon loans and wishful thinking, the odds of such a cataclysm wiping out your 10% capital buffer and then some are vanishingly low.

And even if it did, your regulator is unlikely to high-five you for sitting on a 15% buffer when 12% would have sufficed and the other 3% could have been used to actually serve members. You don’t get a trophy for hoarding potential.

The worst-case scenario your board keeps preparing for has a name: it’s called opportunity cost. And it’s happening right now, quietly, while you congratulate yourselves on your capital ratio.

“But the Regulators Like It!”

Sure. And your dentist likes it when you floss twice a day. Doesn’t mean it’s a viable identity.

Yes, regulators appreciate strong capital. But they also value operational effectiveness, loan growth, membership value, and risk-informed decision-making. They don’t want to see you building capital castles while the market passes you by.

Running a credit union solely to appease your examiner is like designing a car for your mechanic. Sure, they’ll love the engine access, but no one’s going to buy the thing.

There is a term for what happens when capital accumulation becomes the mission rather than the means: pathological aversion to lending. It shows up in your Call Report. It shows up in your loan-to-share ratio. And eventually it shows up in your membership numbers, as the members who actually needed a credit union found one that wasn’t afraid to be one.

Strategic Growth: Now Hiring Capital

Every dollar sitting in capital at a 14% ratio—when 10% would suffice—is a dollar not deployed into strategic initiatives. That’s a new loan program not launched, a branch not modernized, a digital upgrade not implemented, a member segment left underserved.

You are, quite literally, overcapitalized and underutilized. That’s not caution—it’s stagnation dressed up as virtue.

And CEOs? If your board is holding you hostage with ultra-conservative capital policies, congratulations: you’ve been promoted to Chief Preservation Officer. Your job is to sit on a pile of money and politely decline to use it. You will be evaluated on how well the pile stays piled.

That’s not strategy. That’s surrender with excellent documentation.

The PR Problem You Didn’t Know You Had

There’s also a transparency problem with excessive capital. NCUA Call Reports are public. Peer comparisons are available to anyone who cares to look. And when your capital ratio sits at 15% while your peers are competing effectively at 10%, people start asking questions.

Why is this credit union sitting on all that capital?

Is it strategic discipline? Institutional caution? Or is it, perhaps, a board that has quietly confused accumulation with achievement—and hasn’t noticed that the members stopped benefiting from either?

The story the market tells about an overcapitalized credit union is rarely flattering. It usually rhymes with “afraid” or “stuck.” Neither is a brand position worth defending.

So, What Should a Board Do?

Ah, finally, solutions. You were getting anxious, weren’t you?

  1. Set a capital target, not a capital shrine. Create a realistic, risk-informed capital target based on actual scenario modeling—not vibes, not trauma from the Great Recession, not the vague sense that more is always better. A target implies a ceiling. A shrine implies worship. Know the difference.
  2. Regularly reassess the buffer. If you’ve carried 300+ basis points of excess capital for five consecutive years, that’s not a buffer—that’s a moat. And you’re the dragon asleep in the middle, guarding assets your members can’t access and your mission can’t use.
  3. Tie capital deployment to strategy. Capital should be the fuel for your mission, not a museum piece. Lend it. Invest it. Modernize with it. The cooperative model was not designed to produce the tidiest balance sheet in the graveyard.
  4. Educate the board—yes, again. A board stuck in the “more is always better” loop may need a structured conversation about how capital, risk, and growth actually interact. This is not an insult. It is a fiduciary necessity. Hoarding is not a strategy. It is a habit. And habits can be broken.

Closing Thoughts from Your Favorite Snarky Consultant

No one is asking you to gamble with your capital. Prudent reserves matter. Regulatory compliance matters. The ability to weather a genuine storm matters.

But don’t confuse risk management with strategic paralysis. The real danger isn’t the next economic downturn—it’s the slow erosion of relevance while your capital ratio quietly creeps toward 16% and your members quietly wonder why nothing ever changes. Why the rates aren’t better. Why the app still looks like that. Why the loan got declined when the bank down the street said yes.
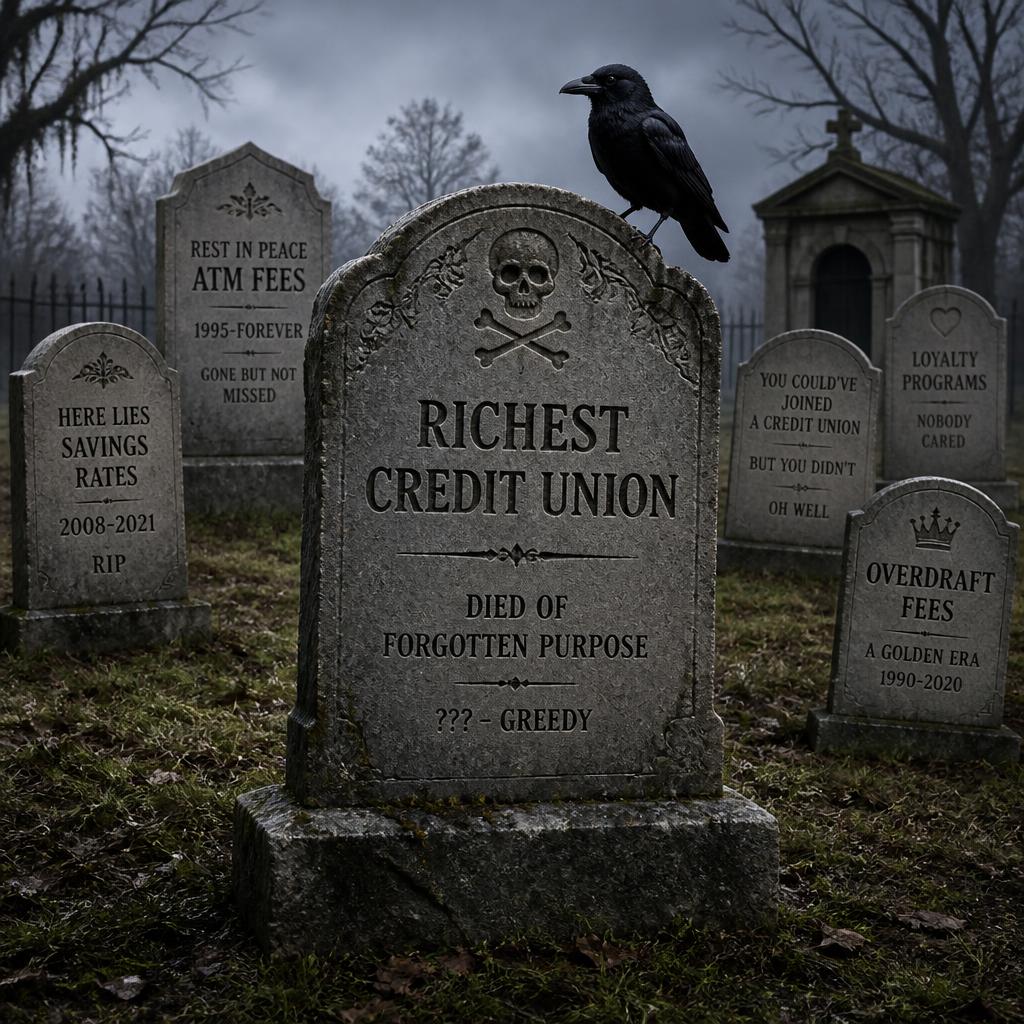
So be brave. Be strategic. Be willing to sweat a little. And for the love of all that is cooperative and not-for-profit, stop worshipping at the altar of excessive capital.

Because in the end, the goal isn’t to die the richest credit union in the graveyard.

It’s to live boldly enough that your members actually notice.

———

Word count: ~1,100

Organic Growth Isn’t Dead: A Memo for Boards Who Think Mergers Are the Only Muscle Left

Remember when your credit union’s growth strategy didn’t involve acquiring the one across town and calling it “synergy”? Those were quaint times — like rotary phones, free toasters, and when “branch transformation” meant adding a fake ficus and a new carpet pattern.

Today, we’re told growth equals mergers. “Economies of scale!” they say. “Efficiency!” they say. And indeed, there’s nothing like doubling your size overnight to make the chart at the annual meeting look like a hockey stick. But here’s the uncomfortable truth: a merger may make you bigger, but it doesn’t always make you better.

And sometimes it doesn’t even make you… you.

By TEAM Resources

The Myth of Mergers as Growth

Let’s be clear: mergers have their place. When done thoughtfully, they can combine complementary strengths, fill product gaps, and offer long-term sustainability. When done reflexively, they can resemble two tired swimmers clinging to each other in a riptide.

Many credit union boards have quietly accepted the idea that “organic growth” — growing through relevance, innovation, and member engagement — is no longer realistic. They assume the game is now about consolidation and survival. After all, “everybody’s doing it.”

This mindset, while understandable, is also a slow surrender of the cooperative DNA that made the movement powerful in the first place. It replaces local connection with administrative convenience. It trades story for scale. And while scale can buy a lot of things, authentic member loyalty isn’t one of them.

When Bigger Isn’t Better

If we were brutally honest, some credit union mergers are like two people getting married mainly because they both happen to dislike dating.

Yes, the combined institution gets a larger balance sheet, a few operational efficiencies, and an expanded field of membership that looks great in a press release. But culture? Mission clarity? Member intimacy? Those things often end up as “non-core assets” quietly written off in the post-merger accounting.

A common board refrain goes something like this:

“We’re not getting enough new members. We can’t keep up with technology. Our growth has stalled. Maybe a merger is our best strategic option.”

Translation:

“We’re not sure how to adapt, so let’s find someone else who’s also not sure how to adapt and see if we can confuse the regulators into thinking it’s progress.”

The Case for Organic Growth (Yes, Still a Thing)

Organic growth isn’t flashy. It doesn’t make headlines. It requires patience, curiosity, and the courage to look uncomfortably inwards. But it is the only kind of growth that builds lasting strength — because it’s rooted in actually being valuable to your members.

Here’s what that looks like in real life:

  1. Deepening Existing Relationships

Your best source of growth is usually the people who already like you. Radical concept, right? Yet many boards are so focused on attracting new members that they overlook the gold mine of existing members who would do more business if someone just asked.

How well do you know your members’ needs today — not when they joined 15 years ago? Are you still talking to them about car loans while they’re quietly launching small businesses or planning retirement?

The most successful credit unions in 2026 will be those that treat data like empathy fuel — not marketing ammo.

  1. Rediscovering Niche Markets

Some of the strongest growth stories in the credit union system right now are small or mid-sized institutions that found their “tribe.” They serve gig workers, healthcare staff, teachers, or specific communities — and they know them inside out.

It turns out that serving a niche exceptionally well beats serving everyone marginally. That’s not just a marketing slogan; it’s a governance philosophy. A board that knows its niche can make strategic bets with confidence instead of wandering through market trends like tourists without a map.

  1. Partnership as Leverage, Not Rescue

    Levers (simple machine)

Partnership doesn’t have to mean merger. It can mean shared back-office systems, fintech collaborations, or joint community projects that expand reach without erasing identity.

The future of cooperative finance might look less like “big fish eats small fish” and more like “schools of fish swimming in coordinated patterns.” (And yes, some of those fish will have better mobile apps than others.)

  1. Relevance Before Reach

Before you try to grow, be worth growing. Members today — especially younger ones — care about whether their financial institution reflects their values.

If your credit union’s last community post was a check presentation in 2018, you might have a relevance problem. Organic growth flows naturally from authenticity: people join and stay where they feel understood, not where they’re sent a quarterly postcard.

Boards: The Gatekeepers of Growth Strategy

Here’s the tricky part — this isn’t a CEO problem alone. Boards often unconsciously reinforce merger dependency. Why? Because mergers feel strategic — they check the “action taken” box.

But true strategic leadership asks harder questions:

  • What do we offer that members can’t get elsewhere?
  • How are we measuring member engagement and satisfaction, not just balance sheet growth?
  • If we weren’t allowed to merge for five years, how would we grow?

That last one is the killer question. It forces creativity, relevance, and discipline. It also reveals whether your credit union has a living strategy or just a growth habit.

When Identity Becomes a Footnote

Mergers change more than logos. They change purpose. When your credit union merges, what happens to your origin story? Your local legacy? The member who remembers when the teller knew their dog’s name?

Those intangible assets are part of your capital base, too — just not in a Call Report cell. And once they’re gone, they’re gone.

This doesn’t mean every merger is bad. Some are necessary and even noble. But the problem arises when boards stop asking the “why” and focus only on the “how fast.”

Because once your identity is gone, growth becomes just arithmetic. And arithmetic is not a mission.

Signs Your Board Might Have Merger Tunnel Vision

  • Every strategic discussion eventually ends with “maybe we should merge.”
  • Your marketing budget is smaller than your merger legal fees.
  • You call it “scale” but secretly mean “retirement plan for the CEO.”
  • The board hasn’t discussed organic member growth in three fiscal years.

If any of these sound familiar, it’s time for a governance intervention.

The Organic Growth Mindset

Reclaiming organic growth doesn’t require a radical overhaul — just a shift in perspective:

  • Growth isn’t a transaction. It’s a relationship.
  • Bigger isn’t safer if it makes you forget who you are.
  • Strategy means deciding what not to chase.
  • Relevance is renewable — if you pay attention.

Boards that embrace this mindset will not only survive but thrive, because they’ll be steering institutions that members actually want to belong to.

Final Thought: The Return of Cooperative Courage

The credit union movement was born from local people solving local problems — together. No one merged their way into that success.

So before your next “strategic partnership exploration committee” meeting, ask yourselves: Are we still in the business of cooperation, or have we quietly pivoted to consolidation?

Because organic growth isn’t dead. It’s just waiting for its board to remember what it looks like.

And spoiler alert: it looks a lot like courage.


Plans from Which We Deviate: The Joys of Strategic Planning for Credit Unions

By Kevin Smith

“Plans are useless, but planning is indispensable.” – Dwight D. Eisenhower.

Dwight D. Eisenhower

Dwight D. Eisenhower

Dwight D. Eisenhower, a man who knew a thing or two about logistics, once made this insightful remark about planning. Since his time, the philosophy of planning has evolved, giving us NASA’s Dr. Laura Gallaher’s version: “Plans from which we deviate.” If that isn’t the most honest and depressingly accurate description of strategic planning, I don’t know what is.

Dr. Laura Gallaher

Dr. Laura Gallaher

For credit unions, strategic planning is not just a fun corporate retreat where executives pretend to be excited about PowerPoint slides. It’s an annual exercise in educated guesswork, wishful thinking, and attempting to predict the future with the accuracy of a weather forecast in the middle of hurricane season. The real value of planning, as Dr. Gallaher puts it, is not the document itself, but the process of thinking through how to react when reality inevitably ignores our best-laid plans.

The Art of Predicting the Unpredictable

Strategic planning is often presented as a structured and rational process, but let’s be real: it’s an exercise in educated fortune-telling. Credit unions operate in a world where economic shifts, regulatory changes, technological advancements, and the ever-evolving expectations of members make long-term planning feel like building a sandcastle at high tide.

Consider the many external factors credit unions must navigate:

  • Economic downturns: Because nothing says “stable financial future” like an unpredictable market.

  • Regulatory changes: Just when you think you understand the rules, a new compliance update appears like an unwanted sequel to a bad movie.

  • Technology disruptions: Fintech startups and AI-powered everything are here to remind you that whatever system you’re using is probably already outdated.

  • Member expectations: People want convenience, security, personal service, and cutting-edge tech—all at the same time, immediately, and preferably for free.

Given these moving targets, it’s no wonder that strategic plans are more useful as artifacts of optimism rather than actionable roadmaps.

The Illusion of Control

One of the great myths of strategic planning is that it gives leaders a sense of control. You can map out all the goals, objectives, and key performance indicators you want, but at some point, reality will step in and say, “That’s cute.”

It’s much like plotting a cross-country road trip with detailed stops and scheduled breaks, only to find that half the roads are under construction, your GPS reroutes you through a cow pasture, and your car develops an unexplained rattling noise somewhere in Kansas.

At best, a strategic plan gives you a general sense of direction—like a compass in a storm. It helps credit unions establish priorities, allocate resources, and identify potential risks. At worst, it’s a highly polished document that will be revisited in a year just to confirm how wrong everyone was.

The Real Benefit: Learning to Adapt

Dr. Gallaher’s take—that planning is about preparing for deviation rather than rigidly following an agenda—is probably the most useful way to think about strategic planning. The real benefit isn’t in the plan itself but in the discussions, debates, and critical thinking that happen during the process.

Strategic planning forces leadership teams to ask important questions:

  • What will we do if interest rates rise/fall/stay the same but somehow still ruin everything?

  • How do we attract younger members who think a credit union is either a dance club or a medieval trade guild?

  • What happens if our core banking system decides to take an unscheduled vacation?

  • How do we balance personalized member service with the fact that nobody wants to talk to a human anymore?

These conversations are where the real value lies. When (not if) the unexpected happens, a credit union that has engaged in rigorous planning is better equipped to pivot rather than panic.

Embracing the Chaos

So, if strategic planning is essentially about preparing to abandon the plan, does that mean we should stop doing it? Of course not. That would be like saying you shouldn’t wear a seatbelt because you might never get into an accident.

The process of strategic planning fosters collaboration, highlights blind spots, and builds a culture of adaptability. It helps leaders anticipate challenges, even if they can’t predict the exact form those challenges will take.

Credit unions that embrace this reality—those that treat their strategic plans as living, flexible frameworks rather than sacred texts—are the ones that thrive. The key is to plan with the understanding that deviations are not failures; they’re just part of the journey.

Planning as a Necessary Illusion

Eisenhower was right—plans may be useless, but planning is indispensable. And if strategic planning for credit unions has taught us anything, it’s that success lies not in rigid adherence to a document but in the ability to adapt, respond, and move forward even when the best-laid plans go sideways.

So, go ahead and create that beautiful, color-coded, data-backed strategic plan. Just don’t be surprised when reality turns it into a “Plan from which we deviate.” After all, that’s the plan all along.

A Need for Change

 The credit union industry requires an urgent need for evolution of credit unions – a need for change. This is dramatically more extreme today than it has been in our history. Credit unions have reached an era of constant refinement and change despite the effort required to do so. This must become an ever-present mindset or credit unions will be left behind in financial services.

By Tim Harrington

A client CEO recently shared with me that his senior staff complained about fatigue. “We’ve been working non-stop on new projects!” The CEO expressed his shared frustration then added, “And we have to continue at this pace, or we’ll become irrelevant to our members.” That’s a stark reality.

It’s clear that the financial services market continues to change. New entrants such as Paze or technology like AI throw a new wrench in the gears just when you think you’re catching up. Consumers’ tastes and demands follow the new changes causing credit unions to initiate change just to not fall behind.

There is good news in all of this. The 2023 American Consumer Satisfaction Index Survey results showed satisfaction for credit unions improving (but still two points behind banks. Ugh!). A common reason shared for this increase was the quality of the human-to-human service at credit unions. Even as technology changes and imbeds itself further into our lives, each generational cohort still has an occasional need for a human interaction; a human to help, or listen, or teach. Nonetheless, the march of technology goes on.

Some major trends we are seeing:

  1. Fast, online account opening is needed to grow
  2. Moving to AI in lending keeps you in the lending game
  3. Finding new funnels of members and loans brings growth to your door
  4. Branches bring value, but their purpose is evolving

1. Fast, online account opening is needed to grow.

The trend setters in the financial services market are fintechs. To open and fund an account with the leading fintechs takes only a few  

minutes. When we bring this up to our clients, many of them say, “We have an online account opening solution!” But when pressed, they usually say its not as fast as Wells Fargo or Chime. It is true that most credit unions have implemented an online account opening solution. But due to policy restrictions, fraud and cybercrime fears, technological limitations or sometimes, simple lack of awareness, most of these solutions take 10 minutes or more and require either sending documents or waiting for a human to confirm something. This obstacle foils a large number of attempts to open an account. For Generations Y and Z, this makes you too complicated to consider.

Market leaders in the credit union world have a 3-minute online account opening. Three minutes…from start to finish. With online account funding, all the fraud and identity work accomplished in the background or using biometrics or some other reliable identification method, and eliminating that pesky Par Value Share issue.

Oh yes, that pesky Par Value Share thing. Try to make that understandable in your online instructions. Credit unions have that pesky Par Value Share of $5 or $25 to explain to the person trying to open account. That is simply an extra, incomprehensible hurdle for a 25-year-old to overcome.  

How do some credit unions seem to rid themselves of the Par Value Share issue? Well, credit union law requires accounts to be opened with a share account. Credit union law doesn’t say how much that should be, or who has to fund it. The account opening leaders have reduced the Par Value to $1.00 and pay the $1.00 themselves, opening the member’s share savings account for them as an automatic part of the transaction. Isn’t paying a single dollar worth the cost of a new member?

The other technology steps our fastest clients use are above my pay grade. I can’t tell you how they do it, but I can tell you THAT they do it. And when a member comes into a branch to open an account, many of our clients have abandoned the clunky in-branch account opening process and are simply asking the member to pull out their phone. Then the CU rep and the new member open the account on their smart phone together. This has reduced the account opening time significantly and allows the CU rep to talk to the member, identify other needs, and build a deeper relationship. Instead of 20 minutes of looking at a computer and 5 minutes talking to the member, it’s 5 minutes opening the account and 20 minutes spent with the member.

2. Moving to AI in lending keeps you in the lending game.

3d rendering humanoid robot with ai text in ciucuit pattern

Zest AI and Scienaptic, among others, have allowed credit unions to expand their credit tier reach, make solid loans, and approve faster. According to Ron Shevlin at Cornerstone, “Institutions using AI tools can more than triple the credit analysis handled per underwriting full-time-equivalent employee.” I think we can safely say that AI will take over financial institution lending in the next five years.

When a board pushed back on AI lending by one of our multi-billion dollar clients, the Chief Lending Officer in frustration slammed her hands on the table and said, “Let’s face it, AI is better than us.” Having seen how AI was building their portfolio, and the speed advantage it was giving them, she could see that we troublesome humans were just slowing the process down.

Moving to AI in lending also means that current underwriters and lending managers will need to learn to be avid data analysts. The jobs in lending are going to change, and your credit union should start to prepare to provide the training and guidance for this transition.

3. Finding new funnels of members and loans brings growth to your door.

Lending is more and more reliant on 3rd parties. Meeting the borrowing needs of people who live online or at a dealer or retailer is becoming the required norm. The main lending funnels for many credit unions are now 3rd parties. These are for unsecured loans with providers like Upstart, HELOC portals like FIGURE and the “old reliables” of car dealers and Lending Club and dozens of others.

Credit unions have always done well with refinances, and that will come back in the not-too -distant future as rates drop and refinance opportunities resurface. But to get significant volume in loans, you will likely have to seek out 3rd parties to work with more and more.

4. Branches bring value, but their purpose is evolving.

Branches are not making a “come-back”, because they’ve never gone away in importance. Consumers in every age demographic cite the importance of having a branch near them…even if they never plan to use one. And many consumers rarely or never use one. Some of our clients have said, “We should take branches out of our Operating Budget and move them to our Marketing Budget.” There is some truth to that. Branches are a key introducing and reinforcing your brand.

Capital One coffee shops have this figured out. Is this branch model built for check cashing or cash handling? Absolutely not. Capital One cleverly uses an “addictive drug”… caffein, to lure customers in, then they have their well selected “Ambassadors” to “pounce” on the unsuspecting coffee drinker to kindly and professionally ask if they’d like to know anything about Capital One. In watching what Capital One advertises and which branches they are adding around the country, their coffee shop idea must be working.

Credit unions are experimenting with this idea. But the best example is the small, regional banking company, Richwood Bank, headquartered in Richwood, Ohio. They have opened five Richwood Coffee branches in the last 10 years. These branches have attracted new business from all age demographics, and due to their ingenious Richwood Coffee strategy, a customer doesn’t pay for that cup of java. Instead, the customer makes a contribution to a selection of not-for-profits. As a result, customers get coffee and feel good about their contribution, and Richwood Bank draws people into their branches AND has been able to donate over a half-million dollars, of other people’s money, to needy organizations in their communities. Wow. Talk about a win-win.

Change is not Necessary … 

Keep in mind what Edwards Deming once said, “It is not necessary to change. Survival is not Mandatory.” Your credit union needs to keep morphing as the market morphs. You don’t need to copy the “other guy.” What’s best is to experiment and try new ideas with your members to see what works in your markets. Bankers and credit union people haven’t traditionally been known as the “creative types,” but it is time to throw that stereotype out. We credit unions should become the leaders in innovative ideas to connect to people. We need to be “People Helping People” in the fastest, best and most innovative ways.


You Can’t Do Things Differently Without Doing Things Differently

Credit unions as an industry have had to lean in towards rapid change and evolution over the last decade, exacerbated by the pandemic. Boards of directors are starting to (finally) acknowledge the need to try to lean in to these changes. Yet, despite these good intentions, often the lean in turns to lip service when they fail to actually “do things” differently in the boardroom.

By Kevin Smith

There certainly aren’t a lot of silver linings from the pandemic. As a matter of fact, I don’t even like presenting it in this light. But one angle that I think we can all agree on is that credit unions, who aren’t known for their speed in change, found out that they could pivot on a dime when they had to. It was fabulous to see worried credit union leaders and their staffs adapt and figure things out pretty quickly. It’s my hope that we all embrace this as a new skill set and keep flexing that muscle. Indeed, many have.

In that light, we also saw some slow to move boards have their eyes thrown wide at the steps necessary to keep working towards the credit union’s purpose. Directors faced the unsettling predicament and supported their leadership and staff as they made fairly radical moves to keep the organization open and serving members who desperately needed their help. Most rose to the challenge and it was fantastic to watch (stressful as it was).

I Worry About Lip Service (and everything else)

Now when I worry (and I do worry), it’s about falling back into old patterns, inertia and complacency. Mostly what I notice from directors is significant embracing of the language of change, particularly when they talk about their leadership and the operations. But what I’m seeing less is boards leaning in themselves to changing their patterns and approaches in the board room and in their governance work.  

It’s not exactly lip service to embracing change that I see. Board members seem very genuinely supportive of the need for faster evolution and development at the operational level. Though it looks a lot more like lip service in regard to changing at the governance level. The two need to happen in synchrony to be most effective.

Snark Alert

Hence the snarky title of this post: You can’t do things differently, if you don’t do things differently.

  • Does your monthly agenda basically a template reused month to month?
  • Do your board meetings have a very predictable flow?
  • Are the same people talkative (or quiet) without fail?
  • Has your board packet had the same format for, oh, over a decade?

These may be red flags that the board is in a rut.

*(Here’s a fun, or maybe terrible, exercise: Challenge the senior leadership to do the funniest skit possible, while performing as the board of directors. This “court jester” approach will reveal any predictability and stereotypes that bubble to the surface. Warning: you may need thick skin for this, but it will certainly be educational.)

Yeahbuts

Naturally I come prepared for the Yeahbuts.

  • “Yeah, but it took us a long time to develop this approach and it works really well.”
  • “Yeah, but we have a lot of work to do and this is efficient.”
  • “Yeah, but the regulators are expecting xyz.”
  • “Yeah, but you’re suggesting change for change’s sake.”
  • “Yeah, but all of this change is going to cause a lot of extra work for the board and the staff.”

I’m not suggesting reinvention every month, or change for change’s sake only. I am suggesting that the entire board look carefully at what they do, question it, and evaluate it in light of the changes the world has made around you. Make sure that anything that fits the category of “this is the way we’ve always done it” gets careful examination for relevance.

Suggestions for Inspection

  • The board agenda: are there interesting discussions, not just monthly updates?
  • Once a year (or as needed), make a determined effort to refine an element of the board packet that makes it easier. [Some of you may need a full revamp. This is more effort. Tackle it. Others may be able to do a regular tweak.]
  • Board chairs: review the personalities in the room. Find out how to change the dynamics of predictable discussions. (Have a one-on-one chat with all directors and ask them for help.)

Support for the Change-Hesitant

Not everyone embraces change. Some actively push back against it. But the adage holds true: “The only constant is change.” So, I encourage directors to have a discussion to really understand how you may be doing things differently to support the change in the operations. You will need to support and understand those who are resistant and help them face the approach with strength. It’s worth it.

© Copyright 2022 - Site design by Sprout Studio in Madison, WI